
Harry Sit's Blog
September 13, 2026
Using ID.me Login with TreasuryDirect
I received several emails from TreasuryDirect saying that it will replace the existing login system with a third-party service called ID.me. The ID.me login is available on TreasuryDirect’s website today. You can still use the existing login system through October 28, 2026, but ID.me will be the only way to access your account online afterward.
Table of ContentsWhat Is ID.meHow It Works with TreasuryDirectPrivacy ConcernsChange.org PetitionCreating an ID.me AccountSecuring ID.me AccountAbandon TreasuryDirectWhat Is ID.meID.me is a private digital identity provider. It has obtained certifications required by some government agencies. In essence, ID.me ties an email address to a real person by matching an image of the person to a photo ID. Without the image, you can create a login and say who you are, but only submitting a driver’s license doesn’t prove who’s submitting it. ID.me requires seeing you via a selfie or a video call.
ID.me has landed contracts with the IRS, Social Security, VA, and now TreasuryDirect. After you log in with ID.me, ID.me tells the agency positively who just logged in.
How It Works with TreasuryDirectI already have an ID.me account because the IRS requires it to use its IP PIN system (see Stop Tax Return Fraud: Sign Up for the IRS IP PIN Program). I tried my login at TreasuryDirect.
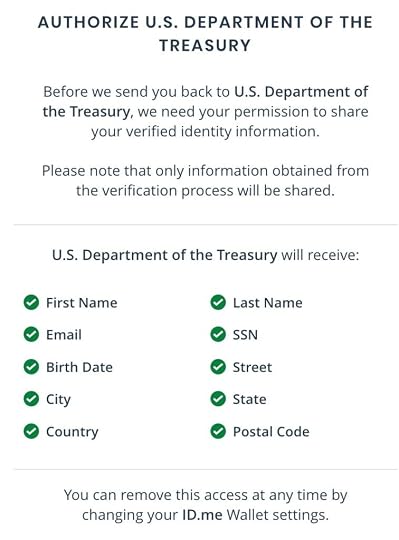
After I logged in through ID.me, it asked for my permission to share these pieces of information it has on me with TreasuryDirect. I wasn’t too concerned with sharing because I had already given these separately to TreasuryDirect when I opened the TreasuryDirect account.
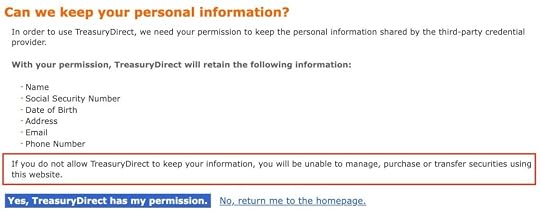
ID.me sent me back to TreasuryDirect. TreasuryDirect asked for permission to retain the information sent over by ID.me. You won’t be able to use the TreasuryDirect website if you don’t give permission.
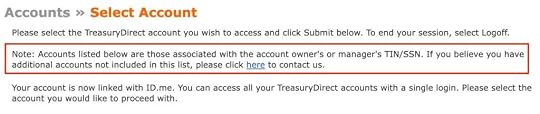
TreasuryDirect uses the Social Security Number sent by ID.me to search for accounts associated with it. Normal account access continues after you choose an account. You may not see this screen if you have only one account under your Social Security Number.
Privacy ConcernsI already have an ID.me account because I was forced by the IRS to create one. It worked smoothly for me at TreasuryDirect.
However, if you don’t have an ID.me account yet, you may be concerned about giving your ID documents and selfie to a private company. It’s a serious concern, but TreasuryDirect is forcing your hand. You won’t be able to access your TreasuryDirect account after October 28, 2026 if you don’t create an ID.me account.
TreasuryDirect says this in its ID.me transition FAQs:
Will I be required to use ID.me to access my TreasuryDirect account online after October 28, 2026?
Yes. After October 28, 2026, ID.me will be the only method to log in to your TreasuryDirect account. You will have the option to use your traditional TreasuryDirect login between September 13, 2026, and October 28, 2026.
If you do not sign up and/or connect your TreasuryDirect account(s) to ID.me by October 28, 2026, you can easily restore online access at any time by completing the ID.me setup process and linking your TreasuryDirect account(s).
Without an ID.me Wallet, you will still be able to manage your account by submitting paper forms. However, you will not be able to:
Sign in to TreasuryDirect online.Make new purchases.Set up new reinvestments of marketable securities. (Existing reinvestments already in place will continue.)View or download your tax forms online.If you need a copy of your Form 1099 for the current tax year, you can request one by mail after the forms become available in January of the following year by contacting TreasuryDirect Customer Support at 844-284-2676 (toll-free).
You won’t be able to make new purchases. You can sell your existing holdings only by submitting paper forms. TreasuryDirect says on its home page that those requests “may take ten months or longer to process.”
Change.org PetitionWaiting ten months or longer to sell existing holdings isn’t a real choice. Some users started a petition at Change.org about this issue. You can sign the petition if you don’t like being forced to create an ID.me account. The petition has received 204 signatures as I’m writing this.
Creating an ID.me AccountI’m not optimistic that TreasuryDirect will listen to the user protests and change course. If you decide to relent, you can create an ID.me account by going to the ID.me website and clicking on the “Sign in” button on the top right.
Be prepared to submit a government-issued photo ID, such as a driver’s license or a passport, and your Social Security card. As I remember it from when I created my account some time ago, ID.me sent me a link to take a selfie. Or you can join a video call with a verifier, who will match your face with your photo ID. The process wasn’t too difficult.
Securing ID.me AccountIt’s crucial to secure your ID.me account because it’s linked to your Social Security Number. If someone logs in to ID.me as you, they will be able to access the IRS, Social Security, and TreasuryDirect as you.
ID.me offers several multi-factor authentication (MFA) methods. I would only consider the three strongest methods.
MFA MethodStrength(Hardware) Security Key on a computerVery StrongNFC Mobile Security Key (requires ID.me Authenticator app)Very StrongPasskeyVery StrongCode Generator (requires ID.me Authenticator app)StrongPush Notification (requires ID.me Authenticator app)ModerateText Message or Phone CallFairUsing a hardware security key on a computer requires buying at least two security keys (one primary, one backup), which cost $29 each. You can use the same two security keys to secure your email accounts and Vanguard account. See PSA: Secure Your Email Account to Prevent Wire Fraud and Security Hardware for Vanguard, Fidelity, and Schwab Accounts.
The NFC Mobile Security Key method requires both the hardware security keys and the ID.me Authenticator app on a mobile phone. It’s not more secure than using a hardware security key on a computer. The ID.me Authenticator app is one more thing to manage, and you probably don’t want it on a phone that you take everywhere anyway.
A passkey is a software version of a hardware security key. It’s stored in a password manager application. If you’re already familiar with using passkeys and a password manager app, it’s as secure as using a hardware security key, and you don’t have to buy hardware keys. Many other websites support passkeys now. It’s good to learn how to use passkeys anyway.
I use hardware security keys with ID.me because I already bought them. Otherwise, I would use a passkey stored in my password manager app.
Abandon TreasuryDirectIf you don’t want ID.me, you have until October 28, 2026 to do anything at TreasuryDirect using your existing login. Otherwise, you will have to use paper forms and wait 10 months or longer.
If you have marketable securities (Treasury Bills, Notes, and Bonds), you can’t sell them before maturity. If they will mature soon, you can turn off automatic reinvestment and wait for the final payment. Make sure your linked bank account is correct and keep the bank account open until you receive every payment from TreasuryDirect. Print or save your current holdings to a PDF, and create calendar reminders for all expected payouts.
If you have savings bonds, you can sell/redeem them as long as they’re older than 12 months since the issuing date. Selling savings bonds triggers taxes on the accrued interest. You can save the page that displays the interest when you sell to a PDF, or you can ask TreasuryDirect to mail you the 1099 forms by calling customer service next year. Be prepared for long hold times if many users choose to call.
You have two bad choices. Either give sensitive information to a private company picked by the government agency or sell everything and pay taxes. I really don’t like this, but I don’t think they will change.
Learn the Nuts and Bolts I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read Reviews
The post Using ID.me Login with TreasuryDirect appeared first on The Finance Buff.


July 22, 2026
2026 2027 Federal Income Tax Calculator for Retirees
A reader suggested that I release my tax calculator for retirees under a separate title because it has outgrown its original purpose.
I initially made a calculator only for the taxable portion of Social Security benefits. Many questions from readers made me realize that they were also looking for the resulting taxes from their Social Security benefits and other income. I added the tax calculation and expanded the scope over time.
Table of ContentsWhy Another Tax CalculatorWhy RetireesWhat’s IncludedWhat’s Not IncludedCalculatorWhy Another Tax CalculatorThere are many tax calculators online already. However, most of them only look backward, not forward. The 2027 tax brackets will be known by September 2026, but most online tax calculators don’t update to 2027 until well into 2027. Because I track tax brackets even before the IRS officially publishes them, my tax calculator will cover next year sooner than any other, giving you an early start on planning.
TurboTax desktop software has a What-If Worksheet for planning (I wrote about it in Tax Planning with TurboTax What-If Worksheet). It works to some degree, but it’s missing some important pieces. Notably, it doesn’t include the ACA premium tax credit for retirees not yet on Medicare. Most other tax calculators online don’t include the ACA premium tax credit either. That’s the case in the popular Dinkytown 1040 Tax Calculator and its licensed clones on AARP and other websites.
Other tax software programs don’t even do 2026 until November, when they release the 2026 version. The early releases are often still incomplete at the time. In general, tax software is intended for filing, not for planning.
AI is quite good these days, but as I wrote in Which AI Calculates Taxes Correctly?, a tax calculator is faster and more accurate than AI if you know which one to use.
Some niche tax calculators update early and are more complete. Case Study Spreadsheet and Excel1040 are two good ones I know. I wrote about Case Study Spreadsheet in Roth Conversion with Social Security and Medicare IRMAA. Both Case Study Spreadsheet and Excel1040 require more upfront setup, though. The calculator I made is less comprehensive but easier to get a quick calculation.
Why RetireesI specifically made this tax calculator only for retirees.
Retirees’ taxes are simpler. They don’t have deductions and credits related to children and education, such as the Child Tax Credit, Child and Dependent Care Credit, American Opportunity Credit, or the Student Loan Interest Deduction. The calculator can be made simpler when I don’t need to include inputs for those things.
Meanwhile, retirees have a greater need for a tax calculator to set up withholding and estimated tax payments. They also have more control over the sources of their income. Taxable income can come from IRA withdrawals, capital gains, or Roth conversions. A tax calculator is helpful to compare different approaches.
What’s IncludedThis calculator covers pretty much everything relevant to retirees:
Social Security benefitsMuni bond interestQualified dividends and long-term capital gainsRentals, interest, non-qualified dividends, short-term capital gainsWages, pension, IRA withdrawals, Roth conversionsQualified Business Income deduction (from self-employment or REIT dividends)Net Investment Income TaxAbove-the-line deductionsStandard DeductionCash donations made directly to charitiesSenior DeductionItemized deductionsNon-cash donations and donations to Donor Advised FundsState and local taxes (SALT) paidMedical expensesMortgage interestACA Premium Tax CreditI picked these for their relevance to retirees. The less-used itemized deductions and ACA tax credit are collapsed by default. You can easily skip those if you don’t have them, but you can still dive in when you do.
What’s Not IncludedBesides things not relevant to retirees, this calculator doesn’t cover these items:
Self-employment taxAlternative Minimum Tax (AMT)Foreign Tax CreditThese are more complicated, and most retirees don’t have them. Collecting inputs to calculate them would make the calculator more crowded for the vast majority of users. In addition, the calculator only calculates the federal income tax. It doesn’t calculate state and local taxes.
CalculatorThe calculator does both 2025 and 2026. You can double-check the 2025 results against your filed 2025 tax return. When you see that the calculator is correct for 2025, you’ll be confident that it’s also correct for 2026. I’ll update it to include 2027 as soon as I have a good handle on the 2027 tax brackets.
.section-toggle { cursor: pointer; user-select: none;}.section-toggle .arrow { display: inline-block; transition: transform 0.2s; margin-right: 4px; font-style: normal;}.section-toggle.collapsed .arrow { transform: rotate(-90deg);}Calculating for Tax Year 20252026
Tax Filing Status: Single
Head of Household
Married Filing Jointly
Married Filing SeparatelyI’m 65 by 12/31Spouse (if filing jointly) is 65 by 12/31Social Security benefits (gross, annual):Investment Income:– Muni bond interest– Qualified dividends and long-term capital gains– Other investment income (rentals, interest, non-qualified dividends, short-term capital gains, …)Other income (wages, pension, IRA withdrawals, Roth conversion, …):Active Qualified Business Income included above (self-employment with material participation):Other Qualified Business Income included above (199A dividends, business income without material participation):Above-the-line deductions. These include deductible contributions to HSA, traditional IRA, SEP-IRA, and SIMPLE IRA, and deductible self-employment tax and self-employment health insurance. Most retirees don’t have these.Cash donations made directly to charities (outside of QCD): ▼Itemizing Deductions (expand if you think you may itemize instead of taking the standard deduction) – Non-cash donations and donations to Donor Advised Funds– State and local taxes– Medical expenses– Other itemizable deductions (mortgage interest, …)ACA health insurance (check if you’re on ACA health insurance):– Household size– State of residence: Lower 48 Alaska Hawaii– Full price of the policy chosen (monthly)– Net price after the subsidy (monthly)– Full price of the second-lowest cost Silver plan (monthly)– Number of months on ACA policy during the year
$ of your Social Security benefits is taxable, which means % of your benefits is tax-free.
Your federal income tax is approximately $.
This is calculated from a taxable income of $ (AGI $ – Standard Deduction $Itemized Deductions $ – QBI Deduction $ – Senior Deduction $ – charitable contribution deduction $). The calculated tax includes $ in Net Investment Income Tax and $ in .
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post 2026 2027 Federal Income Tax Calculator for Retirees appeared first on The Finance Buff.
April 8, 2026
Transfer Money to Another Person with Push-Only ACH/EFT
As I mentioned in a previous post — Pay Someone By Zelle: Daily Limit and Recurring Payments — the ACH system in the U.S. is set up to be bidirectional by default. A routing number and an account number can be used to both deposit money into the account and withdraw money from it.
This makes it difficult to transfer money to another person’s account because people don’t want to reveal their bank account number, fearing you might take their money. As a result, person-to-person transfers are typically done through third-party services such as Venmo, Zelle, PayPal, or Cash App. Both parties must use the same service. You can’t do it if you have Venmo and they have Zelle. Either you must also sign up for Zelle, or they must also sign up for Venmo.
Each third-party service has its limitations. They work for smaller transfers, but they often don’t work for larger ones. Bank of America limits Zelle transfers to $3,500 per day. If you want to transfer $5,000, you’d have to split it into two days. Many banks have even lower Zelle transfer limits than Bank of America.
Trusted PartiesSome people don’t mind sharing their bank account information with you when they know and trust you. Say you’re giving annual gifts to your adult children, or you’re paying a mom-and-pop landlord monthly. They’re willing to give you their bank account for you to deposit into. Even then, it’s not that easy to transfer money to their account.
Many banks only allow linking to accounts that you own. They require verification to confirm that you have control over the target account. It’s done traditionally by micro-deposits. Lately, many banks have moved to using instant verification services such as Plaid or Mastercard Data Connect (formerly Finicity). This requires logging into online banking at the target bank. Banks see who owns the target account in this process. They won’t allow the link when names don’t match.
Intra-Bank TransfersSome banks support transfers between customers within the same bank. Many credit unions also have this feature. They call it member-to-member transfers. Suppose your child is attending college out of state. If both of you have accounts at the same bank or credit union, you can transfer to your child’s account internally.
It’s feasible to make this arrangement with a child. It’s difficult to do with your sister or a landlord unless you happen to use the same bank.
Bill Pay or Mail a CheckYou can use Bill Pay to pay an individual. The Bill Pay provider will mail a paper check. Or you can mail a check yourself. Both are subject to delivery delays and potential loss or theft. That’s not a good way.
Wire TransfersYou can also send a wire transfer, but many banks charge a fee for wires. Even if you get free wires from your bank, many banks also charge a fee for receiving a wire. Making your family member or the landlord pay a $15 fee to receive money from you isn’t that great.
Push-Only ACHFortunately, some banks allow linking to another person’s bank account. They don’t require ownership verification for this type of link when they disallow withdrawing money from the target account. For instance, when you link an external account to Bank of America, it asks you whether you want the account to be “only transfers to” or “for transfers to and from.”
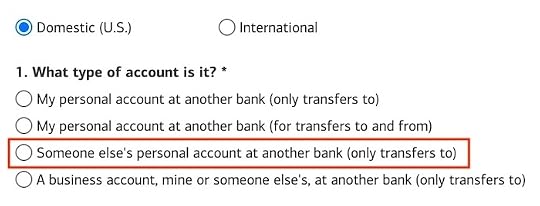
Selecting “for transfers to and from” requires ownership verification through Plaid. Selecting “only transfers to” doesn’t. If you use Bank of America, see the detailed walkthrough in How to Link an Account to Bank of America for ACH Push.
FidelityI use Fidelity for my banking (see 2 Ways to Use Fidelity as a Bank Account). I can link another person’s bank account to my Fidelity account. Like Bank of America, Fidelity asks whether the account is owned by me or by someone else.
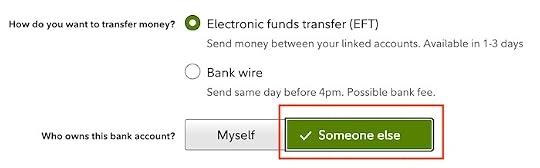
Linking a bank account you own creates a bidirectional link: you can push money to that account or pull money from it. It requires ownership verification. Linking a bank account owned by someone else creates a push-only link: you can transfer money to that account, but you can’t withdraw from it. It doesn’t require ownership verification.
Fidelity will go through a banking industry process called “prenote” to confirm that the target account is valid. A prenote requires waiting at least 3 business days before sending the first transfer. Give it about a week of setup time before you need to transfer money. Once the link is fully set up, the transfer arrives on the same business day if you request it early enough in the morning, or on the next business day if you miss the cutoff. It’s almost as fast as a wire transfer, and it’s free to receive.
You can transfer up to $100,000 per day by EFT/ACH from a Fidelity account. It’s not possible to transfer that much by Venmo or Zelle.
Fidelity’s online interface only supports ad hoc transfers to another person’s account. You can’t schedule transfers for a future date or set up recurring transfers to another person, whereas you can set up scheduled or recurring transfers to your own accounts. If you need to set up scheduled or recurring transfers to another person, call customer service to see if they can set it up on their side.
***
Venmo or Zelle works well for buying things listed on Craigslist or Facebook Marketplace, or paying a gardener or a house cleaner. They don’t work as well for transferring larger amounts to a trusted party. Having an account that supports ACH to another person’s account makes it work in that scenario. The receiving side doesn’t require any special setup. They only need to give you their routing number and account number. It’s free on both sides.
If your bank also supports ACH transfers to another person’s account, please include its name in the comments so other readers know where to go besides Fidelity and Bank of America.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post Transfer Money to Another Person with Push-Only ACH/EFT appeared first on The Finance Buff.
Better Than Venmo and Zelle: Transfer Money with ACH/EFT
As I mentioned in a previous post — Pay Someone By Zelle: Daily Limit and Recurring Payments — the ACH system in the U.S. is set up to be bidirectional by default. A routing number and an account number can be used to both deposit money into the account and withdraw money from it.
This makes it difficult to transfer money to another person’s account because people don’t want to reveal their bank account number, fearing you might take their money. As a result, person-to-person transfers are typically done through third-party services such as Venmo, Zelle, PayPal, or Cash App. Both parties must use the same service. You can’t do it if you have Venmo and they have Zelle. Either you must also sign up for Zelle, or they must also sign up for Venmo.
Each third-party service has its limitations. They work for smaller transfers, but they often don’t work for larger ones. Bank of America limits Zelle transfers to $3,500 per day. If you want to transfer $5,000, you’d have to split it into two days. Many banks have even lower Zelle transfer limits than Bank of America.
Trusted PartiesSome people don’t mind sharing their bank account information with you when they know and trust you. Say you’re giving annual gifts to your adult children, or you’re paying a mom-and-pop landlord monthly. They’re willing to give you their bank account for you to deposit into. Even then, it’s not that easy to transfer money to their account.
Many banks only allow linking to accounts that you own. They require verification to confirm that you have control over the target account. It’s done traditionally by micro-deposits. Lately, many banks have moved to using instant verification services such as Plaid or Mastercard Data Connect (formerly Finicity). This requires logging into online banking at the target bank. Banks see who owns the target account in this process. They won’t allow the link when names don’t match.
Intra-Bank TransfersSome banks support transfers between customers within the same bank. Many credit unions also have this feature. They call it member-to-member transfers. Suppose your child is attending college out of state. If both of you have accounts at the same bank or credit union, you can transfer to your child’s account internally.
It’s feasible to make this arrangement with a child. It’s difficult to do with your sister unless you happen to use the same bank.
Bill Pay or Mail a CheckYou can use Bill Pay to pay an individual. The Bill Pay provider will mail a paper check. Or you can mail a check yourself. Both are subject to delivery delays and potential loss or theft. That’s not a good way.
Wire TransfersYou can also send a wire transfer, but many banks charge a fee for wires. Even if you get free wires from your bank, many banks also charge a fee for receiving a wire. Making your family member or your landlord pay a $15 fee to receive money from you isn’t that great.
Push-Only ACHFortunately, some banks allow linking to another person’s bank account. They don’t require ownership verification for this type of link when they disallow withdrawing money from the target account. For instance, when you link an external account to Bank of America, it asks you whether you want the account to be “only transfers to” or “for transfers to and from.”
Selecting “for transfers to and from” requires ownership verification through Plaid. Selecting “only transfers to” doesn’t. If you use Bank of America, see the detailed walkthrough in How to Link an Account to Bank of America for ACH Push.
FidelityI use Fidelity for my banking (see 2 Ways to Use Fidelity as a Bank Account). I can link another person’s bank account to my Fidelity account. Like Bank of America, Fidelity asks whether the account is owned by me or by someone else.
Linking a bank account you own creates a bidirectional link: you can push money to that account or pull money from it. It requires ownership verification. Linking a bank account owned by someone else creates a push-only link: you can transfer money to that account, but you can’t withdraw from it. It doesn’t require ownership verification.
Fidelity will go through a banking industry process called “prenote” to confirm that the target account is valid. A prenote requires waiting at least 3 business days before sending the first transfer. Give it about a week of setup time before you need to transfer money. Once the link is fully set up, the transfer arrives on the same business day if you request it early enough in the morning, or on the next business day if you miss the cutoff. It’s almost as fast as a wire transfer, and it’s free to receive.
You can transfer up to $100,000 per day by EFT/ACH from a Fidelity account. It’s not possible to transfer that much by Venmo or Zelle.
Fidelity’s online interface only supports ad hoc transfers to another person’s account. You can’t schedule transfers for a future date or set up recurring transfers to another person, whereas you can set up scheduled or recurring transfers to your own accounts. If you need to set up scheduled or recurring transfers to another person, call customer service to see if they can set it up on their side.
***
Venmo or Zelle works well for buying things listed on Craigslist or Facebook Marketplace, or paying a gardener or a house cleaner. They don’t work as well for transferring larger amounts to a trusted party. Having an account that supports ACH to another person’s account makes it work in that scenario. The receiving side doesn’t require any special setup. They only need to give you their routing number and account number. It’s free on both sides.
If your bank also supports ACH transfers to another person’s account, please include its name in the comments so other readers know where to go besides Fidelity and Bank of America.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post Better Than Venmo and Zelle: Transfer Money with ACH/EFT appeared first on The Finance Buff.
Better Than Venmo and Zelle: Transfer Money with Push-Only ACH
As I mentioned in a previous post — Pay Someone By Zelle: Daily Limit and Recurring Payments — the ACH system in the U.S. is set up to be bidirectional by default. A routing number and an account number can be used to both deposit money into the account and withdraw money from it.
This makes it difficult to transfer money to another person because people don’t want to reveal their bank account number, fearing you might take their money. As a result, person-to-person transfers are typically done through third-party services such as Venmo, Zelle, PayPal, Cash App, etc. Both parties must use the same service. You can’t do it if you have Venmo and they have Zelle. Either you must also sign up for Zelle, or they must also sign up for Venmo.
Each third-party service has its limitations. They work for smaller transfers, but they often don’t work for larger ones. Bank of America limits Zelle transfers to $3,500 per day. If you want to transfer $5,000, you’d have to split it into two days. Many banks have lower Zelle transfer limits than Bank of America.
Trusted PartiesSome people don’t mind sharing their bank account information with you when they know and trust you. Say you’re giving annual gifts to your adult children, or you’re paying a mom-and-pop landlord monthly. They’re willing to give you their bank account for you to deposit into. Even then, it’s not that easy to transfer money to their bank account.
Many banks only allow linking to accounts that you own. They require verification to confirm that you have control over the target account. It’s done traditionally by micro-deposits. Lately, many banks have moved to using instant verification services such as Plaid or Mastercard Data Connect (formerly Finicity). This requires logging into online banking at the target bank. Banks see who owns the target account in this process. They won’t allow the link when names don’t match.
Intra-Bank TransfersSome banks support transfers between customers within the same bank. Many credit unions also have this feature. They call it member-to-member transfers. Suppose your child is attending college out of state. If both of you have accounts at the same bank or credit union, you can transfer to your child’s account internally.
It’s feasible to make this arrangement with a child. It’s difficult to do the same with your sister unless you happen to use the same bank.
Bill Pay or Mail a CheckYou can use Bill Pay to pay an individual. The Bill Pay provider will mail a paper check. Or you can mail a check yourself. Both are subject to delivery delays and potential loss or theft. That’s not a good way.
Wire TransfersYou can also send a wire transfer, but many banks charge a fee for wires. Even if you get free wires from your bank, many banks also charge a fee for receiving a wire. Making your family member or your landlord pay a fee to receive money from you isn’t that great.
Push-Only ACHFortunately, some banks allow a push-only link for ACH/EFT. They don’t require ownership verification for this type of link when they disallow withdrawing money from the target account. For instance, when you link an external account to Bank of America, it asks you whether you want the account to be “only transfers to” or “for transfers to and from.”
Selecting “for transfers to and from” requires ownership verification through Plaid. Selecting “only transfers to” doesn’t. If you use Bank of America, see the detailed walkthrough in How to Link an Account to Bank of America for ACH Push.
FidelityI use Fidelity for most of my banking (see 2 Ways to Use Fidelity as a Bank Account). When you link a bank account, Fidelity asks whether it’s owned by you or by someone else.
Linking a bank account you own creates a bidirectional link; you can push money to that account or pull money from it. It requires ownership verification. Linking a bank account owned by someone else creates a push-only link. You can transfer money to that account, but you can’t withdraw from it. It doesn’t require ownership verification.
Fidelity will go through a banking industry process called “prenote” to confirm that the target account is valid. A prenote requires waiting at least 3 business days before sending the first transaction. Give it about a week of setup time before you need to transfer money. Once the link is fully set up, the transfer arrives on the same business day if you request it early enough in the morning, or on the next business day if you miss the cutoff. It’s almost as fast as a wire transfer.
You can transfer up to $100,000 per day by EFT/ACH from a Fidelity account. It’s not possible to transfer that much by Venmo or Zelle.
Fidelity only supports one-time transfers on push-only links. You can’t schedule transfers for a future date or set up recurring transfers to another person, whereas you can set up scheduled or recurring transfers to your own accounts.
***
Having an account that supports push-only ACH to another person’s account makes it easy to transfer a larger amount than using Venmo or Zelle. The receiving end doesn’t require any special setup. They only need to give you their routing number and account number. It’s free on both sides.
If your bank also supports push-only ACH transfers to another person’s account, please include its name in the comments so other readers know where to go besides Fidelity and Bank of America.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post Better Than Venmo and Zelle: Transfer Money with Push-Only ACH appeared first on The Finance Buff.
March 21, 2026
Which AI Calculates Taxes Correctly?
Several readers asked me whether they could use AI to calculate taxes after reading my previous post AI Gives Better Answers Than Google. They want a tax projection to help with setting tax withholding, paying estimated taxes, or planning for Roth conversions.
My first reaction was that calculating taxes isn’t the best use of AI, because it falls under “verifiable facts” and “latest development” categories. The retirement plan contribution limits, tax brackets, the maximum deduction amounts, etc., are all verifiable facts. The IRS sets them every year, and they are what they are. Just go to the IRS website for the latest numbers or Google. If you ask AI, it had better get the latest numbers online anyway, because AI’s training lags.
On the other hand, tax rules are complicated. Even when you have all the latest numbers from the IRS, you still need to apply the complex rules — what counts and what doesn’t, and which rates apply to which income. Online tax calculators usually don’t cover the current year until late in the year, and they can be either too simple or too complicated. It would be nice to have AI calculate taxes specifically for the types of income and deductions we have: not too simple with only limited inputs, and not too complicated with everything under the sun.
The QuizI thought I would test how well AI calculates taxes. I came up with this quiz question:
Jill, single, age 63, has these incomes in 2026:
$30,000 from Social Security$10,000 from interest and pre-tax IRA withdrawals$37,000 from qualified dividends and long-term capital gains$1,000 from muni bond interestJill contributes $4,400 to her HSA and donates $1,500 in cash to charities. What’s Jill’s federal income tax in 2026?
I designed this question carefully to cover several calculations. Less than 85% of Social Security is taxable. The income consists of ordinary income, tax-exempt income, and investment income taxed at preferential rates. Ordinary income goes across two tax brackets. So does investment income. One deduction is above-the-line, and the other is below-the-line.
I added these instructions to encourage AI to get the latest tax numbers from the IRS:
Initial ResultsIt’s important to calculate it accurately. Please use tax amounts only for 2026 and only from official IRS sources.
I sent the quiz to all four major AI chatbots. I only used the free version in each one, with the free Thinking, Pro, or Expert mode enabled. I compared the answers to the correct result from my calculator in Calculator: How Much of My Social Security Benefits Is Taxable?
Correct Answer$1,640ChatGPT 5.4 Thinking Mini$325Gemini 3 Pro$1,910Claude Sonnet 4.6 Extended$1,910Grok 4.20 Expert$1,910My quiz was too hard! All four major AI models failed to give the correct answer. The $1,500 cash donation threw them off. It falls squarely in the “latest development” category. The charity donation deduction for non-itemizers is new. The AI models all have “donations are deductible only when you itemize” imprinted in their training. Gemini, Claude, and Grok all would have given the correct answer if I hadn’t included the cash donation. ChatGPT was off on how much of Social Security is taxable.
When you see AI not giving you a deduction, you can point it out. I followed up with this hint:
I heard that cash donations are deductible for people using the standard deduction, starting in 2026, up to a limit.
I also added this for ChatGPT:
Round 2Another AI model calculated a different amount for how much Social Security is taxable. Please double-check your calculation to see who’s right.
All chatbots double-checked and revised their answers.
Correct Answer$1,640ChatGPT 5.4 Thinking Mini$1,640 Gemini 3 Pro$1,411Claude Sonnet 4.6 Extended$1,640 Grok 4.20 Expert$1,411
ChatGPT and Claude got the correct answer. Gemini and Grok treated the cash donation deduction as above-the-line and used it to reduce the Social Security taxable amount.
I asked Gemini and Grok to clarify which item should be included in the calculation and which shouldn’t be. Gemini didn’t realize its mistake. Grok refused to answer because I reached the message limit for not having an account.
Here are the full chat transcripts if you’re interested:
https://chatgpt.com/share/69bf73fb-db44-8004-9905-b77b56fbb6ce
https://gemini.google.com/share/795bdad9f5ad
https://claude.ai/share/ef62408a-6502-4d70-82be-6ea46a4a4cc3
[No sharable link for Grok because I don’t have an account.]
ImpressionsI don’t think we can draw definitive conclusions based on only one test. I call these impressions.
1. Whether AI can calculate taxes correctly depends on the complexity. 3 out of 4 major chatbots would’ve given the correct answer in one go if the question didn’t include the new and tricky charity donation deduction.
2. AI works better when you continue the conversation. Both ChatGPT and Claude reached the correct answer after I asked them to double-check.
3. It takes little effort to send the same question to two or more AI models. You don’t need to know which AI is right when you get different answers. You can tell one AI that another AI said something different. It’ll take a second pass and re-examine.
4. AI was wrong because human sources were wrong. Gemini and Grok treated the donation deduction as above-the-line because many human sources incorrectly called it above-the-line. If you Googled, you would encounter those incorrect sources too. ChatGPT and Claude used more reliable sources and correctly identified the difference between above-the-line and not requiring itemizing deductions.
5. An online tax calculator is faster and more accurate if you know which one to use. That’s a big “if.” Only saying “Don’t use AI because it’s often wrong” doesn’t say where you will find more reliable sources.
As much as I’d like to see everyone use my tax calculator, let’s face it: 99.99% of people don’t know that I exist. They have little chance to find the few sources that do it accurately because Google doesn’t rank tax calculators by accuracy. Short of finding the good sources, the results from AI aren’t that bad (see #1).
6. Even when AI was wrong in some nuances, its general approach was correct. All 4 AI chatbots followed these correct steps:
Calculate how much of Social Security is taxableCalculate AGICalculate taxable incomeSeparate ordinary income and preferential investment income, and know how they stackApply different tax bracketsThese are what I call “common knowledge of an insider.” You can learn these steps from AI if you’re not familiar with tax calculations. That’s more valuable than just having a final number. An online tax calculator gives you a number but doesn’t explain the steps. AI is a better tool if you’re more interested in learning how to fish than getting a fish.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post Which AI Calculates Taxes Correctly? appeared first on The Finance Buff.
March 12, 2026
AI Gives Better Answers Than Google
One of the most significant technological breakthroughs in the last few years is AI. It started with chatbots writing essays and creating cute images. Now it’s everywhere. It’s above my pay grade to comment on what AI will do to jobs, the macroeconomy, or the markets. I can only share how AI has helped me at the micro level.
The experiences I’m sharing below were with ChatGPT. I used ChatGPT only because it came out first. There are at least four major AI chatbots now. I believe another AI would’ve done just as well. I’m currently experimenting with other AI models to see which one I like better for which tasks.
AI Detected Mysterious Power UsageI bought a house without an agent last December, but I hadn’t moved in right away. The first month’s electricity bill came and showed that an empty house used more electricity than the house I lived in. I asked AI what could have caused such high usage. It gave me some likely causes and a method to find the culprit: turn off breakers one at a time and watch for large drops at the electric meter.
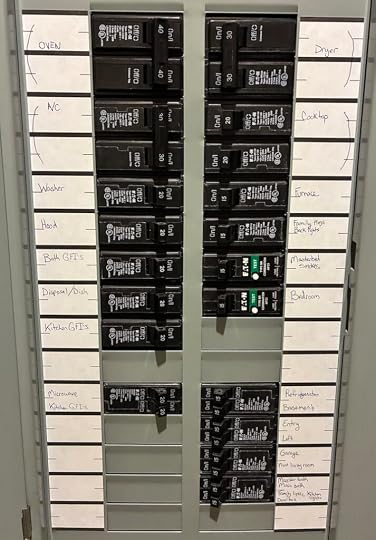
AI could read the handwriting on the breaker panel to tell me which breaker is more suspicious than another. It taught me how to read the current load from the electric meter to see whether the mysterious power consumption was on the breaker I just turned off.
Sure enough, I found it. The previous owner had ice-melting roof cables running 24/7 without any switch or sensor. My electricity usage dropped by 15 kWh per day after I unplugged the de-icing cables.
AI Reconfigured Water Heater RecirculationNext came the natural gas bill. It also showed high usage while I had already set the thermostat to 60 when the house was unoccupied. I asked AI again. It quickly zeroed in on the water heater after it asked me about the gas appliances in the house. It turned out that the recirculation setting in the tankless water heater was set to “always on.”
Turning off recirculation would lower the natural gas bill, but it also would make me wait longer for hot water. I asked AI for a compromise. It said my water heater model supports an on-demand mode using wired push buttons (like doorbell buttons) to activate recirculation as needed. Wiring requires too much work. I asked AI for a wireless solution. It told me to make this:
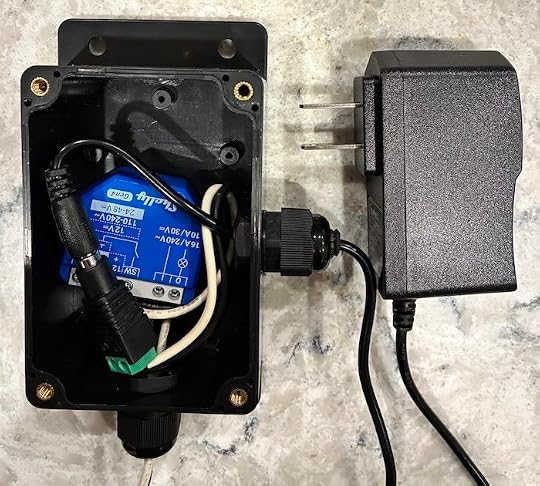
A 12V power adapter powers a Shelly 1 smart switch, stored in a plastic project box, with a hole drilled on two sides to attach cable glands. Wireless motion sensors in the kitchen and bathrooms trigger the smart switch, which activates recirculation. I had never heard of any of these components before, except for the power adapter.
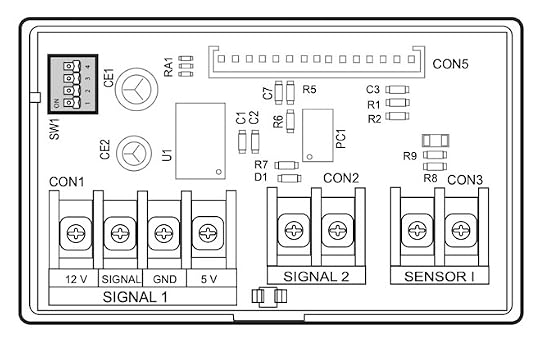
I sent AI this diagram of the control board from the water heater’s instruction manual to ask whether I could skip the 12V power adapter and use the 12V contact in the SIGNAL 1 terminal on the control board. It read the diagram and gave me good reasons why it could work, but it was safer to use an external power adapter and connect the switch to the SIGNAL 2 terminal.
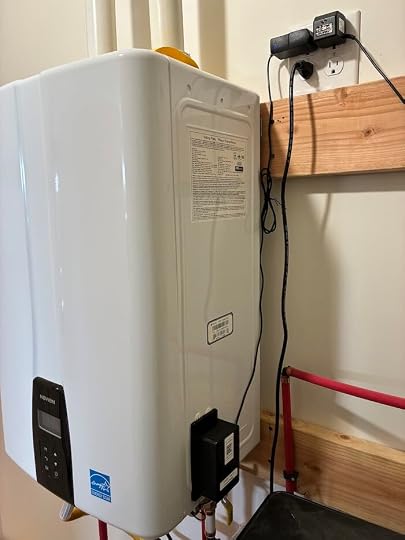
AI’s solution worked. On-demand activation reduced natural gas consumption by 1 therm per day versus running recirculation 24/7.
AI Dimmed Exterior LightsI gave AI another problem that bugged me. My exterior lights on the sides of the garage door were too bright. I couldn’t simply change the bulbs because the lights don’t have bulbs. They use integrated LEDs. They were controlled by a dusk-to-dawn photocell. I couldn’t put them on a dimmer because there was no switch for them inside the house.
AI told me to look for a junction box where I could place a dimmer. I couldn’t find the junction box it wanted, but I found a switch for a porch light that was also downstream of the photocell. I asked AI whether I could merge the garage lights onto that switch. It gave me a cautious “maybe,” with a list of conditions to confirm behind the switch cover.
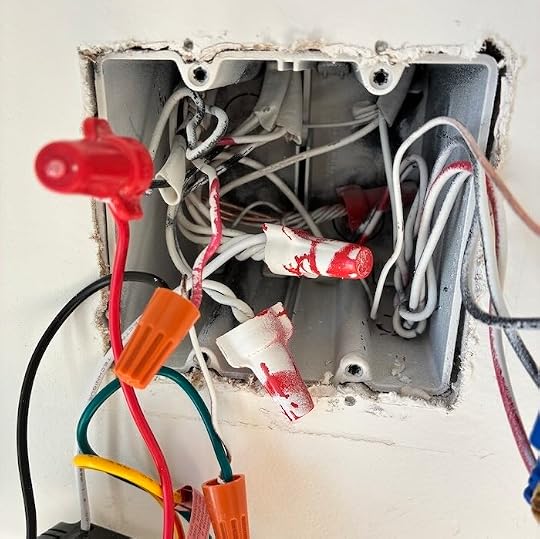
I took the cover plate off and sent a photo to AI. It read the wires and confirmed that moving the wires would comply with the National Electrical Code.
Long story short, AI guided me in rewiring the lights at the switch and installing a smart dimmer. Those exterior lights by the garage door aren’t too bright anymore.
AI Knows More Than the Average PersonAll of the above may be too basic for some of you, but it was all new to me. I didn’t know what neutral wires looked like before I engaged with AI. I don’t think the average person could have helped me as much as AI. I could have asked an electrician, but AI is free and available 24/7.
AI also answered many questions in vastly different fields. It explained to me why two ducks flew in and out daily with a group of wild geese, and the geese weren’t hostile toward the ducks because they were clearly different species. It also explained why the heads of mallard ducks look green, but the feathers are actually black or charcoal when you look at them on a table.
An electrician can help me with wiring, but I don’t think the average electrician knows about ducks. AI knows more than the average person because it represents the aggregate knowledge of the Internet.
AI Is Better Than GoogleGoogle was a technology breakthrough in the early 2000s. Google made it much easier to find information on the Internet. Most readers of this blog found me directly or indirectly through Google. I’m grateful to Google for connecting all of us, but from a user’s perspective, AI is better than the traditional Google search.
You Google something and find a source. The source may be addressing something related, but not necessarily exactly what you’re looking for. It may require some background knowledge that you don’t have. You Google again and find another source. The two sources may supplement each other, but also contradict. Sometimes you can leave a comment to ask for clarification. The author may or may not reply. I can’t possibly keep up if every reader of this blog asks me a clarifying question. I’m sure many people reading my posts left with unanswered questions.
The user experience with AI is much better. You can ask AI in long paragraphs and give more context. You can upload photos to explain and clarify. AI tailors the answer to your question and context. You can ask follow-up questions. AI remembers the conversation. You can pick up where you left off from days before.
The solutions to my problems in this post all happened over several days. AI pointed me in a direction. I went there and reported back what I found. It then gave me the next steps. It was like having an on-call consultant. I don’t think I could have achieved the same results as easily with traditional Google searches.
Google knows this. Google prominently features its Gemini AI when you use Google Search now. It has to do it to stay relevant.
Ask Follow-Up QuestionsYou get more out of AI when you keep asking follow-up questions. The more you ask, the more specific the answers will be to your exact needs and constraints.
AI didn’t come up with the entire solution to my water heater recirculation problem in one go. The conversion started with what was burning so much natural gas. After I turned off recirculation, the next question was why that setting was enabled and how I could still get the benefits without running it 24/7.
AI brought up wired buttons. I asked for a wireless alternative. AI gave me the smart switch. When I asked how I would power it, AI said to tap into 110V power. I read the switch’s manual, which said it could also use 12V DC. I asked AI whether that would be a better way. AI said “Yes!” although it didn’t give me this better way when I first asked.
I then asked how to tell which wire from the 12V adapter is positive and which is negative. AI said it’s easier if I use a barrel tip adapter. I asked where to put the switch and wires. AI told me about the project box and the cable gland.
A full solution only emerged after these rounds of questions.
Don’t Dismiss AI for InaccuraciesSome people dismiss AI, saying it’s just a probability-based text generator, and it can’t be trusted because it’s often wrong. Indeed, AI isn’t always accurate. The average person or the average Google search result isn’t always accurate either.
Looking up verifiable facts isn’t the best use of AI. AI is best at giving you the common knowledge of an insider. The less you know about a subject, the more you should use AI, because it fills your knowledge gap quickly. You don’t need 100% accuracy when the gap is so huge. A total market index fund or a 60/40 allocation is common knowledge for seasoned investors. We can debate whether they are the best, but they make a good baseline for people unfamiliar with investing.
Are AI’s solutions to my electricity usage, water heater, and lighting problems “the best”? Maybe not, but I only needed working solutions, not necessarily the best solutions. AI got me there quickly.
Dismissing AI only because it’s not always accurate is short-sighted and throwing the baby out with the bathwater.
AI for Finance, Investing, and TaxesMany questions in finance, investing, and taxes don’t have definitive answers. The “best” move requires knowing the future.
AI doesn’t know the latest development. When the 2025 Trump tax law was still being crafted, AI’s answers were often wrong (so were many media reports). Again, asking AI about verifiable facts isn’t the best use of AI. AI does a better job of explaining things and applying knowledge to specific situations.
I asked AI this fairly complicated question from the Bogleheads forum about Traditional versus Roth contributions for a self-employed person and the interplay with ACA health insurance. Here are the answers from ChatGPT and Claude:
https://chatgpt.com/share/69b1cc1c-b69c-8004-b118-6eb8b2ea32b0
https://claude.ai/share/7f1e5c63-e00b-44f2-8f3b-e23bbfb7405c
I posted the question verbatim to AI before any human answered it on the forum. AI couldn’t have cheated. If I rate how I would answer the question myself at 100, I would rate AI’s answers at 90+. Those were only AI’s initial answers. The answers will improve with more follow-up questions. I’m sorry to say that the first two replies from humans on the forum weren’t as good as AI’s answers. The discussion would be more productive if humans used AI’s answers as a baseline and built upon them.
Next time you have a question, start with AI. Use AI less for verifiable facts and not for the latest development, but more for how to apply knowledge to your specific situation. The less you know about a subject, the more AI will help. It gives you a good baseline. Keep asking follow-up questions. The more you ask, the better the answers will be. Supplement the good baseline from AI with human sources when necessary, but start with AI.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post AI Gives Better Answers Than Google appeared first on The Finance Buff.
January 13, 2026
A Simple Annual Financial Review Template
The start of a new year is a good time to recap the previous year and plan for the current and future years. My wife and I just did the annual financial review for our household. I’m sharing the template we use and where we get the data.
Net Worth
The total net worth represents all financial resources available at a point in time. We break it down into two categories: liquid investments (“paper assets”) and real estate. The value for real estate is net of any mortgage balances. We include home equity in total net worth because it is an available financial resource. We love our home, but when necessary, we can sell and buy a less expensive home or use the proceeds to fund assisted living. We use the historical purchase cost as the value for real estate. You can also use the property tax assessment value or a reasonable estimate.
We further break down liquid investments between taxable investments and retirement accounts. You can add a third category to break out Traditional versus Roth accounts if you’d like.
We get these values from Fidelity’s Full View, which aggregates both Fidelity and non-Fidelity accounts. I updated my post Fidelity Full View + Analysis: Track Your Portfolio Across All Accounts with Fidelity’s latest user interface, also known as the New Full View. The New Full View doesn’t have all the features of the Old Full View, but it still works for our purpose.
We round to the two most significant digits in these numbers. $1.3 million or $250k is good enough. It’s not necessary to go more granular.
Investment Allocation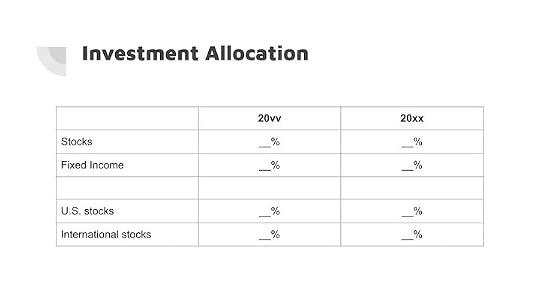
Next, we look at the investment portfolio’s asset allocation at the highest level: stocks versus fixed income, and U.S. stocks versus international stocks. This tells us how it changed from the previous year and whether we need to rebalance.
We get these numbers from Fidelity’s Analysis feature, which I described in the second half of Fidelity Full View + Analysis: Track Your Portfolio Across All Accounts. Analysis examines the investment holdings from all accounts in Full View. You can use other tools or a spreadsheet.
Income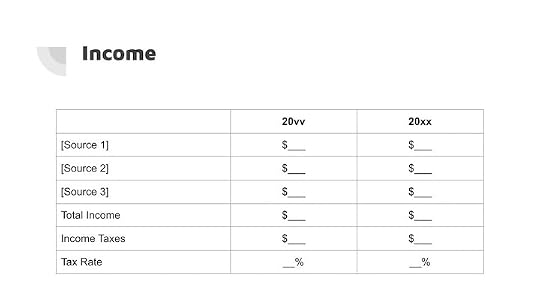
This is our tax return boiled down to its simplest form. What are the major sources of income? How much do we pay in taxes? How much is it as a percentage of our total income?
We get the income numbers from Microsoft Money, which was discontinued many years ago but still runs in Windows 11. Any other income and expense tracking software works as well. Taxes for the prior year are from the actual federal and state tax returns. Taxes for the year that just ended are estimated.
Again, use no more than two most significant digits, as in $25k, not $24,736.
Expenses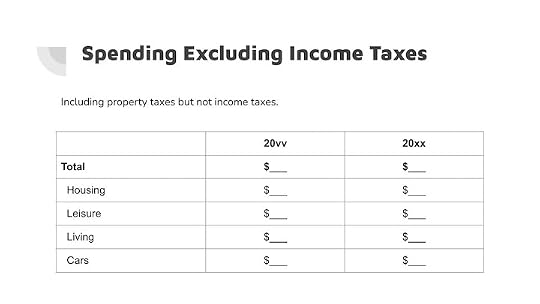
Now we come to the expenses side. We include property taxes but not income taxes as expenses. Income taxes are largely a function of income. The quickest way to lower taxes is to lower income. Income and taxes are already covered in the previous section.
We keep income and expenses in only three or four major categories. Fewer categories present a clearer view without distraction from too many details. The expenses data also come from Microsoft Money. Again, many other income and expense tracking software work too.
Baseline Retirement Projections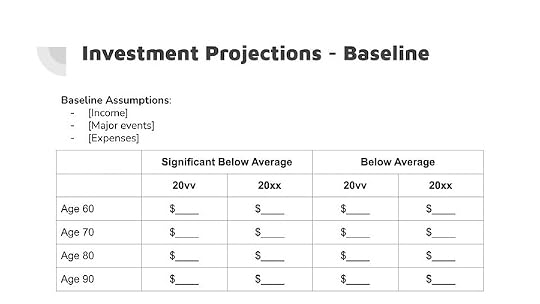
We run a baseline projection in Fidelity’s retirement calculator. I updated my post, Fidelity Retirement Planning Tool: High-Level Model, Not Tactical, with Fidelity’s latest user interface. The retirement calculator uses accounts in Full View assigned to the retirement goal.
The baseline assumptions include our best guesses for income, expenses, and major events. The retirement calculator projects a trajectory of the investment portfolio when market returns are significantly below average or merely below average. I look at the projected values in today’s dollars at major age milestones. Comparing with projections from last year tells us whether we’re off track.
Projections by definition are educated guesses. Anything beyond the single most significant digit in the numbers is meaningless.
Pessimistic Retirement Projections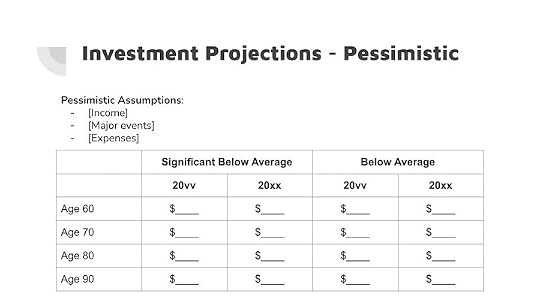
We run the projections again in my wife’s account with a more pessimistic set of assumptions: lower income, higher expenses, and unexpected events. We do it in two accounts because Fidelity’s retirement calculator doesn’t allow saving two scenarios in one account.
The pessimistic assumptions serve as a stress test for the future outlook. What if our best guesses are off significantly? We want our plan to survive these adverse conditions. Running these projections revealed the two fundamental drivers of financial success in retirement.
Summary
Finally, we summarize the previous sections. This recaps the previous year and guides the current year.
We intentionally keep the annual financial review short and simple because we believe it’s most useful to have a big picture. We use Fidelity’s tools and Microsoft Money as data sources, but you can also populate the review with data from other sources.
If you find this format helpful, you can download the template from Google Drive. It’s set as view-only. Please use File -> Download to download it in PowerPoint or ODP format and modify it as desired.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post A Simple Annual Financial Review Template appeared first on The Finance Buff.
December 29, 2025
How I Bought a Home Without an Agent After the NAR Settlement
The rules for residential real estate agent commissions changed in 2024 after the National Association of Realtors (NAR) settled a class action lawsuit.
Table of ContentsBefore the SettlementAfter the SettlementAgent’s Roles for the BuyerAgent’s Roles for the SellerPutting Everything in ActionBefore the SettlementIt used to be that a home seller agreed to pay a commission to a real estate agent to sell a home, and the seller’s agent advertised on the home listing that they were willing to share their commission (typically 50:50) with any agent who brought a buyer. The commission rate was usually 6% of the home’s price (5% in some expensive areas).
If a buyer didn’t use an agent, the listing agent wouldn’t share anything. This created an incentive for buyers to use an agent in the same way as credit card rewards created an incentive to use credit cards. When the price was the same whether you used an agent, you might as well use one and get whatever little benefits that may exist.
After the SettlementThe class action settlement required that a buyer and the buyer’s agent sign a written agreement to establish the commission upfront before touring a home. The agreement typically says that the buyer is obligated to pay the commission unless another party covers it. As a result, most sellers lower the seller’s agent’s commission to 3% and anticipate that a buyer will ask for another 3% to cover the commission to the buyer’s agent.
It’s business as usual on the surface. The seller still builds an expected 6% commission into the price. The seller’s agent still receives 3% and the buyer’s agent still gets another 3%. Some consumer advocates were hoping that the NAR settlement would change the landscape in residential real estate and lower commissions. That hasn’t happened for the most part. Redfin reported that the average buyer’s agent commission has risen slightly since the new NAR rules went into effect.
Real estate agents don’t lower their commissions to compete for business from buyers because most buyers don’t choose an agent by price. Buying a home is a big decision, and most buyers want a “good” agent or the “best” agent. The industry sows FUD to make buyers suspect that only unknowledgeable or inexperienced agents are willing to discount their commission, and that not using a “good” agent or the “best” agent will only cost them in other ways more than the difference in commissions.
However, the incentive for a buyer to use an agent is weakened after the rules changed. If a buyer doesn’t use an agent, the buyer can offer a lower price and still make it appealing to the seller.
I did just that. I bought a home without an agent, from out of state, over a video walkthrough by FaceTime. I paid less and still beat competing offers.
Agent’s Roles for the BuyerBefore you consider going alone without a buyer’s agent when you buy a home next time, you should understand the roles of a buyer’s agent and be prepared to fill those roles in another way.
Personal ShopperA buyer’s agent acts as a personal shopper for the buyer, especially when the buyer isn’t familiar with the area. When I bought my first home with an agent before the Internet age, I didn’t know which homes were for sale. Only agents had access to listings. She drove me in the back of her Mercedes from one house to another.
The Internet replaced this role. When I worked with an agent before the NAR settlement, the agent never brought to my attention any listing I didn’t already know from my saved searches on Zillow and Redfin. Instead, I pointed out to her which listings I was interested in and asked her to set up showings.
EducationA buyer’s agent educates a buyer on the legal terminology in the buying process. What’s an offer? What’s a counteroffer? What’s earnest money, and when does it become non-refundable? Which contingencies do you need in a contract, and what happens when the deadline passes? Who pays for what title insurance? What’s an ALTA settlement statement, and how do you read it?
You must educate yourself on these things when you don’t use a buyer’s agent. They’re not that difficult to learn. AI can help.
Resource RecommendationsReal estate agents have contacts for everything. If you need a loan, they refer you to a loan officer or a mortgage broker to get you approved. After you go under contract, they call in an inspector. If the home needs repairs, they have contractor contacts for estimates or to perform the repairs before you move in.
These resources are only referrals. The agent doesn’t cover the cost. You still have to pay each service provider. Keep in mind that an agent’s referrals are optimized for responsiveness, not quality or price. If a picky inspector finds a lot of problems with a home and scares off buyers, that inspector won’t get repeat referrals next time. Time is of the essence in a real estate transaction. The goal of an agent is to keep the deal moving toward closing without delay.
When you go without an agent, you should gather these resources yourself ahead of time. You can find service providers on Google Reviews. Line up contacts to call when you need a loan, an inspection, insurance, a repair estimate, and so on.
Opinion for Quality and ValueBuyers often ask their agent whether a home they’re interested in is “good” or how much their offer price should be. They want their agent to help them avoid a bad purchase or overpaying.
It’s wishful thinking. The best you can hope for is that an agent won’t push you to buy or overpay. It’s against an agent’s economic interest to stop you when you’re already inclined to buy a home, because they only get paid when you move forward. The higher your offer price, the more likely the seller will accept it. It doesn’t matter to the agent which house you buy or how much you pay, as long as you buy one, the sooner the better.
You must make your own judgement. Hire an appraiser to assess a home’s fair value when you’re seriously considering making an offer. Lenders order an appraisal for their own protection when you apply for a loan. Nothing stops you from appraising the property before making an offer. The opinion from a trained, neutral third-party appraiser is much more reliable than the opinion from an agent with a conflict of interest.
An appraiser I used charges $400 for a “desktop appraisal.” The appraiser finds recent comparable sales in the area and adjusts for various factors to calculate an appraised value. It doesn’t require a site visit, and the seller won’t know that you did an appraisal. The price for an appraisal is small potatoes when it guides you to how much you should offer for the property. When you save 3% from a buyer’s agent’s commission, you can afford to pay for a pre-offer appraisal.
NegotiatorMany agents say they’ll help you negotiate the best deal. That’s dubious. Bargaining hard to risk losing a deal is bad for business.
When I made an offer through an agent at one time, the seller countered it by another $30,000. My buyer’s agent said the seller’s counteroffer was “a really generous offer and an excellent value for the home.” She cited market trends, how the property was extremely well cared for, and said that the yard was a big bonus. When I decided to back off for other reasons, the seller came back with an offer that was $25,000 below my original offer.
Going with the agent’s recommendation would’ve cost me $55,000 right there. An agent’s incentive lies in moving toward a transaction, not away from it. It’s wishful thinking to count on an agent to negotiate a good deal for you.
Door OpenerYou can go to open houses without an agent. If a listed home doesn’t hold an open house, you need someone to open the door and let you tour the home. A buyer’s agent performs this role. They have apps for requesting a showing time and receiving a code for the key box.
You’ll have to go through the seller’s agent when you don’t use a buyer’s agent. Industry practice doesn’t allow a buyer to tour a home unaccompanied. The seller’s agent can’t just give you a code and let you into the home alone. The agent has to go there him- or herself or send someone from the office.
Sellers’ agents don’t like the additional work because they perceive unrepresented buyers as unserious tire kickers. Tire kickers with a buyer’s agent at least only waste their own agent’s time. You’ll need to convince the seller’s agent that showing the home to you is worth their time and effort. Understanding the roles of a buyer’s agent for the seller and the seller’s agent will help you do that.
Agent’s Roles for the SellerWhy did sellers’ agents share their commission with a buyer’s agent before the NAR settlement? Why do sellers still agree to pay a commission to a buyer’s agent after the NAR settlement when they’re not required to do so?
A buyer’s agent helps the seller sell their home. That’s why the seller is paying a commission.
Qualify BuyersBuyers’ agents only work with qualified buyers. If a buyer doesn’t qualify to buy a $1 million home, there’s no point for the agent to show $1 million homes to the buyer. When I worked with an agent before, the first order of business was sending me to her lender contact to size me up with a mortgage pre-approval. Sellers know that every buyer a buyer’s agent brings to the home is at least in the realm of buying it.
When you don’t use a buyer’s agent, you must show the seller’s agent that you’re qualified. Obtain a loan pre-approval or proof of funds up front. Offer to send it when you first contact the seller’s agent. The seller’s agent wants to sell the home and earn the commission. They’ll be more motivated when they see you’re a qualified buyer.
Persuade BuyersThe offer-and-counteroffer example I mentioned above illustrates that a buyer’s agent plays an important role in persuading the buyer to purchase the home. A buyer may be skeptical if the same justifications come from the seller’s agent, but they’re more trusting when they hear good things about the home from their own agent, who they think is on their side.
Both the seller’s agent and the buyer’s agent are helping the seller sell the home. Paying a commission to a buyer’s agent is like the seller planting a mole by the buyer’s side. The buyer’s agent is officially the Selling Agent in industry lingo. Let that sink in: a buyer’s agent is the Selling Agent for the seller.
When you don’t use a buyer’s agent, you need to show the seller’s agent that you don’t need much persuasion. You can know so much about a home these days without setting foot in it. Show that you’ve done your homework, you’re ready to make an offer, and seeing the home is only the last step.
Offer to use the seller’s agent to process paperwork if you decide to make an offer. Many agents give sellers a discount if they do both sides of the transaction. A typical arrangement in my area is that the seller pays a 3% commission to list the home, with another 3% reserved for the buyer’s agent. If the listing agent represents both the buyer and the seller, the seller pays 4% instead of a total of 6%. The prospect of earning another 1% motivates the seller’s agent to show the home to you.
Putting Everything in ActionMy wife and I wanted to buy a home. We drove around based on current and past home listings to get familiar with the area. We went to open houses.
We narrowed it down to a few specific neighborhoods and floor plans — how large, how many stories, and which rooms we want on the main floor. We set up custom searches with filters on Redfin to notify us of new listings in a hand-drawn area on the map. I established contact with an appraiser and an inspector in advance.
When Redfin emailed us new listings, we checked the website of the local MLS, which had more detailed information than Redfin. The MLS website gave a breakdown by each floor, for example:
Floor 1: 1,534 sq. ft.Floor 2: 1,014 sq. ft.Total: 2,548 sq. ft.Lot Size: 0.17 Acres3 Total BedroomsFloor 1: 1Floor 2: 23 Total BathroomsFloor 1: 2 FullFloor 2: 1 FullOther Rooms:Floor 1: 1 Living Room; 1 Kitchen; 1 Laundry Room;Floor 2: 1 Family Room;These data points, Google Maps, and the listing photos gave us a good idea of what the listed home was like. We didn’t bother asking to see a home unless it met all our specific requirements. If a home checked all the boxes, we looked up the county’s property tax assessment value using the APN from Redfin. The property tax assessment value served as a sanity check in case the listing price was wildly inflated.
It took some time for a home that met all our criteria to come on the market. It was listed on a Monday morning while we were traveling out of state. I sent this text message to the seller’s agent right away:
Hi [name], I’m interested in your listing at [address]. The photos look great. We’ve been to that neighborhood. We’re pretty sure we’ll make an offer if everything checks out. The only thing is we’re out of town until Sunday. Can we schedule a showing for next Monday? We’re not working with an agent. We can send proof of funds.
The agent replied and offered to do a video showing over FaceTime on Tuesday morning. The video walkthrough confirmed that the home had everything we were looking for. I texted the appraiser and ordered a desktop appraisal.
The appraisal came back at a value higher than the listing price, but it was still lower than the county’s assessed value for property tax. The market price in my area is typically higher than the county’s assessment. I knew that the listing price was intentionally set low to attract more interest and encourage bidding.
I downloaded the real estate purchase contract form from my state Division of Real Estate’s website. I made an offer at the appraised value, with a stipulation that the seller would credit 2% of the purchase price to the buyer at closing. This made it easily comparable to other offers that would ask for 3% to cover a buyer’s agent’s commission. I attached proof of funds.
My formally written offer, which was above the listing price right out of the gate, with full terms and proof of funds, indicated to the seller that I was a serious buyer and I knew the value of the home. The seller also received several competing offers. The prospect of earning a 4% commission instead of 3% motivated the seller’s agent to advocate on my behalf. The seller accepted my offer on Friday after a round of “best and final offers.” It took only four days from listing to contract, before we returned from our travel and physically toured the home. We couldn’t have pulled it off if we weren’t well prepared.
Here’s how my offer came down against the next highest bid (I indexed the purchase price to $500,000 to make the math easier):
CompetitionMeDifferencePurchase Price (A)$500,000$505,000+$5,000Commission to Seller’s Agent (B)$15,000 (3%)$20,200 (4%)+$5,200Commission to Buyer’s Agent (C)$15,000 (3%)$0-$15,000Credit to Buyer at Closing (D)$0$10,100 (2%)+$10,100Net Proceeds to Seller (A – B – C – D)$470,000$474,700+$4,700Cost of pre-offer appraisal (E)$0$400+$400All-in cost to Buyer (A – D + E)$500,000$495,300-$4,700The competing buyer and their agent lost because they were weighed down by the 3% commission to the buyer’s agent. With a 3% headroom to play with, my offer basically split it three ways among the seller, the seller’s agent, and me. The seller received $4,700 more in net proceeds. The seller’s agent earned $5,200 more in commissions. I paid $4,700 less. Win-win-win.
If the seller didn’t receive competing offers, I wouldn’t have offered the extra 1% to the seller, and I would’ve saved even more.
I sent in my inspector after we went under contract. The inspection report came back without major issues. We closed on the purchase.
***
The real estate industry class action settlement created opportunities for prepared buyers to purchase a home without a buyer’s agent. The seller, the seller’s agent, and the buyer all benefit when there’s one less mouth to feed.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post How I Bought a Home Without an Agent After the NAR Settlement appeared first on The Finance Buff.
December 21, 2025
Real Life Experience with a Deferred Fixed Annuity (MYGA)
Back in 2020, I bought a 5-year deferred fixed annuity, also known as a Multi-Year Guaranteed Annuity (MYGA). A MYGA, in essence, is like a CD issued by an insurance company. The insurance company guarantees a fixed rate for a fixed period. I spoke about MYGAs in my April 2021 presentation, Fixed Income Alternatives in a Low-Yield Environment.
I bought the 5-year MYGA because it was paying significantly more than a 5-year CD from a bank or credit union at that time. The MYGA paid 3% a year. The best 5-year CD was paying 1.5%. This MYGA had reached its 5-year guarantee period last month. I ended it and pulled the money back to my Fidelity account.
The insurance company kept all its promises. Everything worked exactly as advertised. The MYGA was illiquid, with a prohibitive penalty if you withdraw more than 10% of the balance each year, but I knew that going in. The insurance company was a little slow in processing paperwork, but it was nothing compared to the slow manual processing at TreausryDirect, which can take from six weeks to ten months.
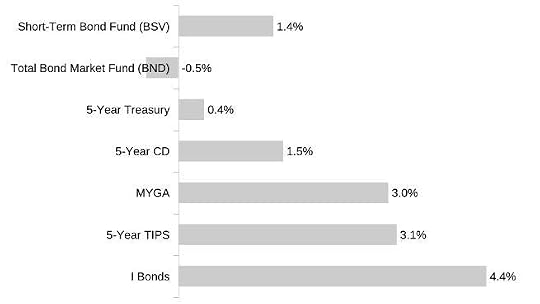 Investment Performance 2020 – 2025
In terms of investment returns, the MYGA did better in these five years than a short-term bond fund, a total bond market fund, a 5-year Treasury, and the best 5-year CD. It trailed a 5-year TIPS by only a hair. I Bonds did better, but they had low purchase limits.
However, I would put my experience with MYGA in the “winning the battle but losing the war” category. That’s why I’m not renewing it or buying another MYGA.
The war is against inflation. Inflation averaged 4.5% a year in the last five years. Because you pay taxes on the gross return, if your tax rate is 25%, you’d have to earn 6% a year to keep pace with inflation. Viewed through this lens, all bond investments lost to inflation in the last five years. The Vanguard Total Bond Market Index Fund had a negative 5-year return before inflation.
Bond SubstitutesBurton Malkiel is the author of the famous book A Random Walk Down Wall Street. He was making rounds in the podcast circle in the summer of 2020 to promote the 12th edition of that book. Mr. Malkiel called the low-interest-rate environment at that time “financial repression.” He suggested lowering the allocation to bonds and investing in preferred stocks and high-dividend stocks as “bond substitutes.”
Burton Malkiel on The Long View podcast, August 2020Burton Malkiel’s suggestion for investing in “bond substitutes” was controversial at that time. Some commentators went so far as to say it was stupid. Now we see the results after five years.
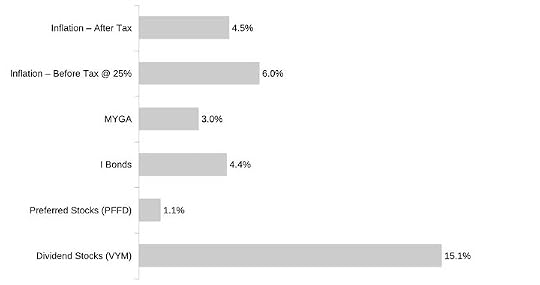 Investment Performance 2020 – 2025
Preferred stocks didn’t do well, but high-dividend stocks did. Investing 50:50 in preferred stocks and high-dividend stocks outpaced inflation both before tax and after tax. Bond substitutes won the war.
The Forest and The TreesMy excursion to MYGA shows that we tend to pay more attention to things that can be analyzed with greater certainty, while neglecting things that are more uncertain but have a more significant impact. I often see people asking questions along these lines:
Which money market fund should I use?
Buy I Bonds in April or May?
Should I invest in Fidelity’s S&P 500 fund (FXAIX) or Vanguard’s S&P 500 ETF (VOO). What about Fidelity’s Zero fund?
TIPS ladder or TIPS fund?
Each question is complicated in its own way if you look at it under a microscope. There’s a powerful spreadsheet that sends you an email alert when it’s time to switch from one money market fund to another. These decisions make a difference, but they easily fall into the “winning the battle but losing the war” category. Before diving into the best place to park your cash, consider whether you should park that much cash in the first place. Then you will avoid a dilemma like this:
Saved up 1 million for a house we are no longer buying, now investing it into the market
The big-picture decisions don’t have an easy answer, but they make a much larger difference when you get them right.
How much to invest in stocks, bonds, cash, real estate, Bitcoin, or gold?
U.S stocks versus international?
Value stocks or growth stocks?
Developed international countries or emerging markets?
Burton Malkiel got the “bond substitutes” right. However, his other suggestions in the same podcast episode for increasing allocation to international stocks and increasing allocation to emerging market stocks within international stocks didn’t pan out. His arguments sounded convincing, and they still do today, but the markets just didn’t accept them.
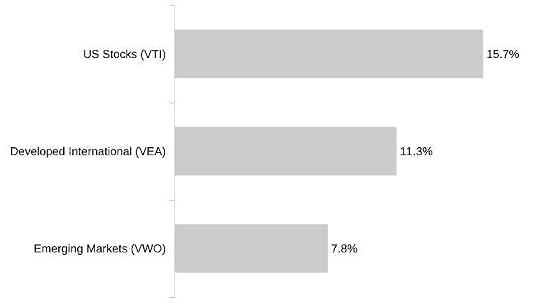 Investment Performance 2020 – 2025
U.S. stocks outperformed international stocks, and developed market stocks outperformed emerging market stocks, both by a substantial margin. How much you invested in US stocks versus international stocks, and in developed international countries versus emerging markets, made a huge difference in the last five years. This is why VTSAX-and-chill was an easy sell.
Maybe it will take more time for those other suggestions from Burton Malkiel to have the last laugh. Maybe they won’t ever catch up. Either way, don’t lose sight of the forest when you examine the trees.
Learn the Nuts and Bolts
I put everything I use to manage my money in a book. My Financial Toolbox guides you to a clear course of action.Read ReviewsThe post Real Life Experience with a Deferred Fixed Annuity (MYGA) appeared first on The Finance Buff.
Harry Sit's Blog

- Harry Sit's profile
- 1 follower
